What Is a Seller Credit, and How Can You Use It When Buying a Home in Stillwater?
Buying a Home Ann Morgan
Buying a Home Ann Morgan
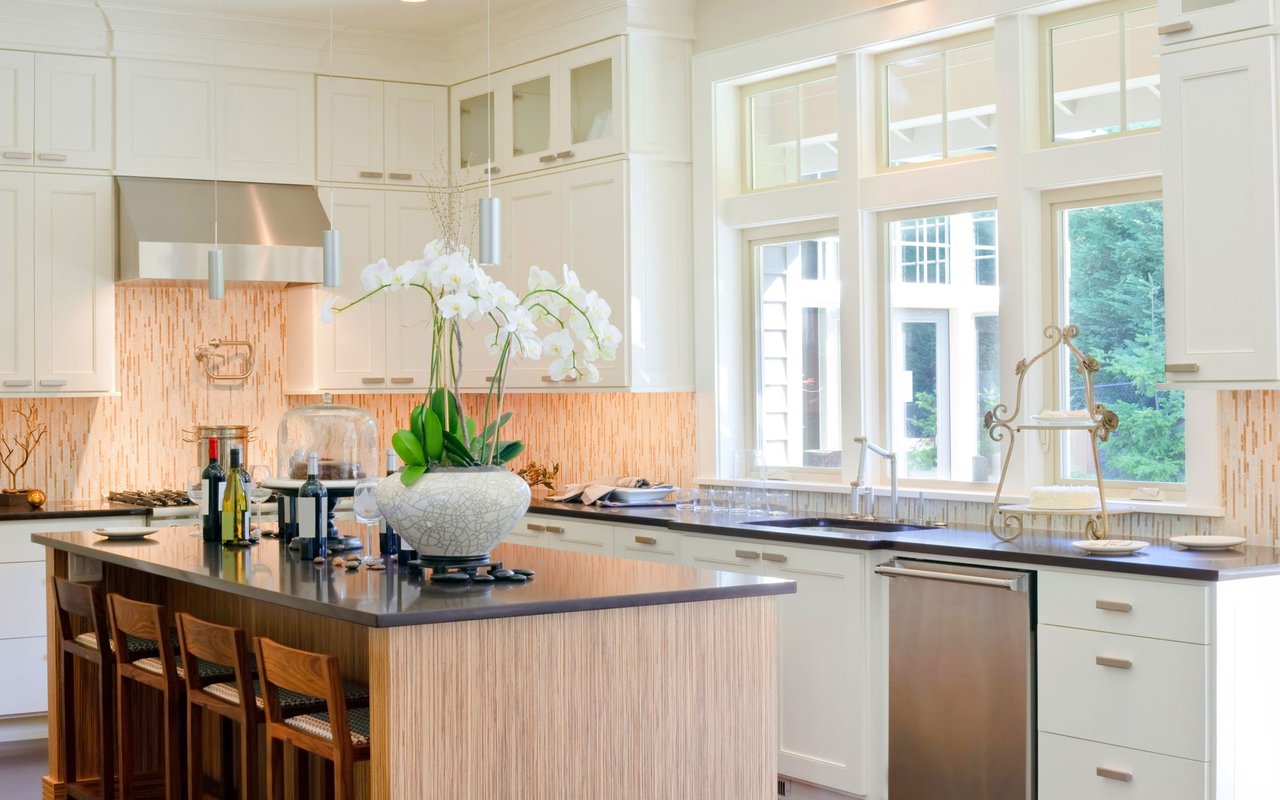
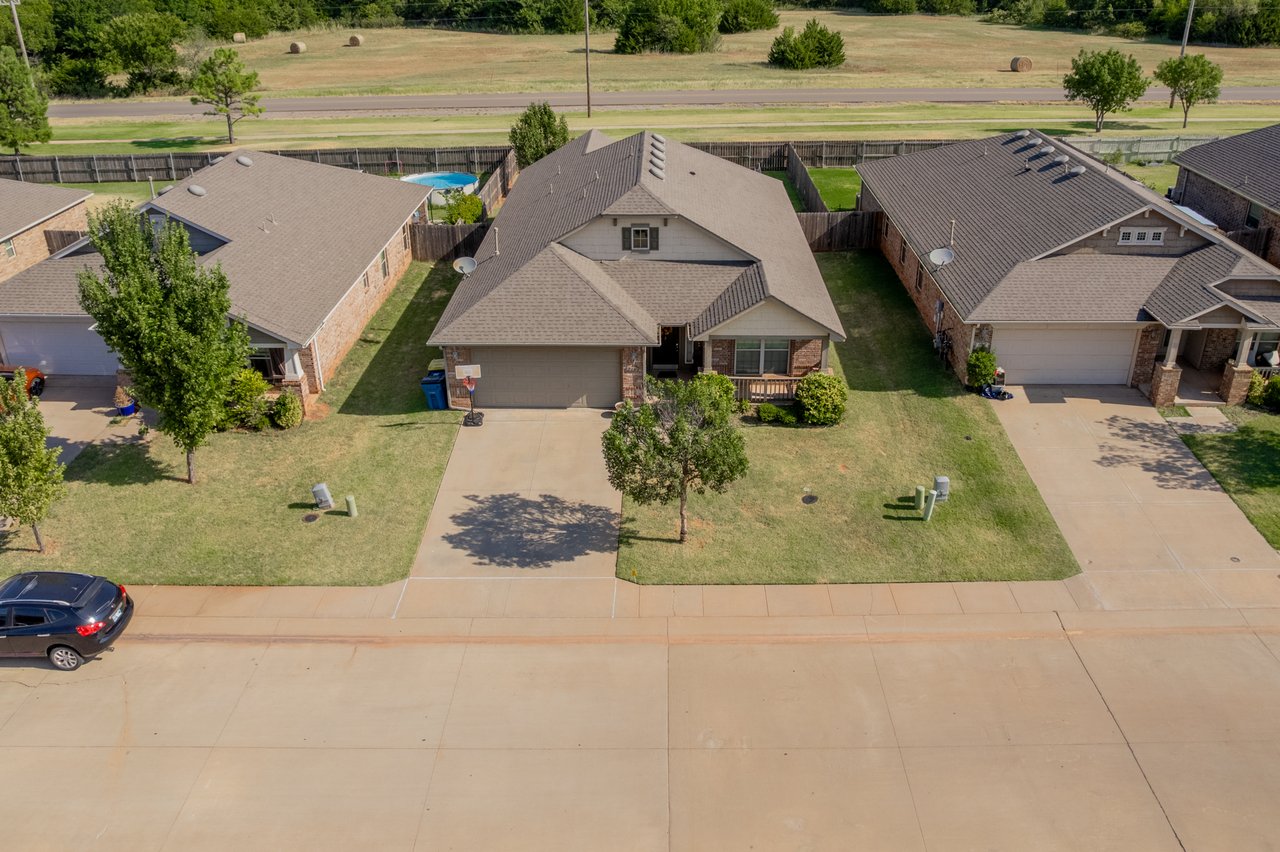
A seller credit is money the seller agrees to put toward your costs at closing. You can usually use it to buy down your interest rate, which lowers your monthly payment for the life of the loan, or to cover closing costs and prepaids like your first year of homeowners insurance and property tax escrow. Right now, two homes I have listed in northeast Stillwater are offering exactly that: up to $7,800 at 218 E Copper Canyon Avenue and up to $7,200 at 1122 E Swim Avenue.
Here's how it works, what it can and can't pay for, and how to figure out which way to use it.
When you write your offer, the credit is written into the contract as an amount the seller will contribute toward your costs. At closing, it shows up on your settlement statement as a credit to you. You never receive it as cash. Instead, it pays bills you'd otherwise pay out of pocket.
The words "with an acceptable offer" matter. The credit is part of the negotiation, so the price, terms, and credit all work together. I'll help you structure it so the numbers make sense for you.
Most buyers use it for one, or a mix, of these:
It depends on two things: how much cash you have for closing, and how long you plan to keep the home and the loan.
Your lender can price out each option so you can see them side by side. If you need a lender recommendation, I'm happy to connect you.
My Buyer's Purchasing Power calculator shows the monthly principal and interest payment at different loan amounts and different interest rates. Enter your loan amount and compare rows to see what a buydown could change for you. Rates in the calculator are for illustration only, so check current rates with your lender.
Yes. Every loan type caps how much the seller can contribute, and the cap depends on your loan program and, for conventional loans, your down payment. The credit also can't be more than your actual closing costs, prepaids, and buydown combined, and any unused amount doesn't come back to you as cash.
Both of these credits are about 2.3% of the list price, which is within the limits for most common loan types. Your lender will confirm exactly how much you can use on your loan.
Seller credit: up to $7,800 toward a rate buydown or closing costs and prepaids, with an acceptable offer.
See 218 E Copper Canyon Avenue
Seller credit: up to $7,200 toward a rate buydown and/or closing costs and prepaids, with an acceptable offer.
If you're relocating or still deciding where in town you want to land, join my Moving to Stillwater Facebook group. I share local guides, new listings, market updates, and answers to the questions people ask most when they're moving here.
Call or text me at 405-614-9600 and I'll set up a showing, connect you with a lender to price out the credit, and walk you through writing an offer that uses it the way that works best for you.
Ann Morgan, REALTOR® | Real Estate Professionals | 405-372-5151 Seller credit amounts are offered by the sellers with an acceptable offer and are subject to lender and loan program guidelines. Information deemed reliable but not guaranteed.
Stay up to date on the latest real estate trends.
Real Estate Market
What the national numbers say, what to check locally, and what to do about it.
Buying a Home
Why the answer depends on how long your student will be here, and what happens after.
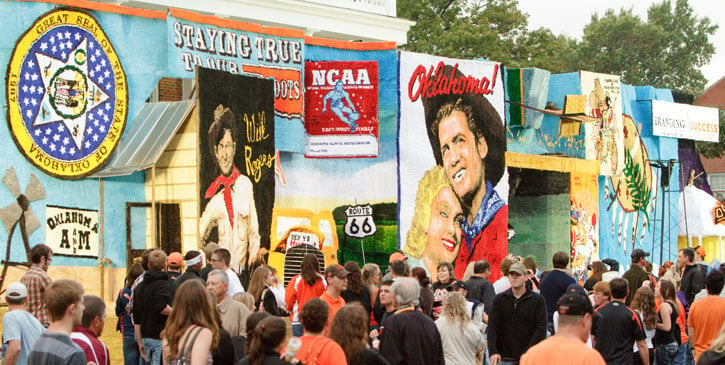
Homecoming week is the best time to see what makes this college town feel like home.
Buying a Home
Two northeast Stillwater homes are offering up to $7,800 to help buyers lower their rate or cover closing costs.
Downtown Stillwater
A monthly night downtown, and an easy way to get to know the town.
Buying a Home
Down payments, rates, negotiating, and new construction, answered.
Buying a Home
What higher rates change, what they don't, and how to run the numbers.
Buying a Home
What actually moves your rate, and how to plan around it.
Buying a Home
A local REALTOR®'s guide to the town, OSU, the outdoors, and where to start.
Get help determining your property's current value, crafting a competitive offer, writing and negotiating a contract, and more. Contact me today.