Pre-Approval vs. Pre-Qualification: What Stillwater Buyers Need to Know
Homes Buying Ann Morgan
Homes Buying Ann Morgan
Pre-qualification is a quick estimate of what you might borrow, based on numbers you tell a lender. Pre-approval is a lender actually checking your income, assets, and credit, and issuing a letter for a specific loan amount. When you make an offer on a home in Stillwater, a pre-approval letter is the one sellers take seriously. I'm a REALTOR® in Stillwater. When I start working with a buyer who's financing, I ask whether they've talked to a lender yet, so there are no surprises later in the search. This is general information. Each lender has its own process, so ask yours what they require.
Pre-qualification | Pre-approval | |
|---|---|---|
What it is | A quick estimate | A lender's review of your finances |
Based on | What you tell the lender | Documents you provide |
Credit check | Often a soft check, or none | Usually a full credit check |
Result | A rough price range | A letter for a specific loan amount |
How long it takes | Minutes to a day | A few days, depending on your paperwork |
How a seller sees it | Weak | Strong |
Lenders use these terms differently, so ask yours exactly what they're offering.
Pre-qualification is a fine first step if you're just starting to think about buying. It gives you a rough idea of your price range without a lot of paperwork. It's not a commitment from the lender, and it doesn't prove anything to a seller.
If you want to run your own numbers first, start with How Much House Can You Afford in Stillwater?.
For a pre-approval, a lender looks at your actual numbers. Expect to provide:
The lender then issues a pre-approval letter that states the loan amount you're approved for, subject to final underwriting. That letter goes in with your offer.
A seller wants to know the buyer can actually close. A pre-approval letter shows that a lender has looked at your finances, so your offer is more believable than one with nothing behind it. In a market where buyers have more choices, as they do now, a stronger offer still stands out, and so does a buyer who has done the homework.
Your pre-approval also helps you. It tells you what range works before you fall in love with a home, and it saves you from finding out later that you don't qualify for that amount. That's the surprise I most want my buyers to avoid.
A pre-approval is not a guarantee that you'll get the loan. The lender still has to underwrite the loan, and the home has to appraise and meet the loan's requirements. Between pre-approval and closing, avoid these:
A pre-approval letter also doesn't last forever. Many expire after a set period, so ask your lender how long yours is good for.
Talking to more than one lender is smart, because rates and fees can differ. When credit checks for a mortgage happen within a short window, they are typically counted together as one inquiry for scoring purposes. Ask your lender how that works, and try to do your comparison shopping within a couple of weeks. For more on what lenders look for, see What Credit Score Do You Need to Buy a Home in Stillwater?.
I’m a REALTOR®, not a lender. I know what rates are doing right now, but I’m not privy to the specific programs or terms each bank offers, and those can be very different from one lender to the next. A lender is the only one who can explain the lending side of the process accurately. That’s why, when I start working with a buyer who’s financing, I ask whether they’ve talked to one. It keeps us from running into surprises during the search, especially if you fall in love with a home and then find out you don’t qualify for that amount.
A lender will also tell you what you can and can’t do while your loan is in process, because every transaction is looked at and accounted for. Before you do any of these, ask your lender:
And until you’ve closed, don’t:
Your lender can tell you exactly what applies to your situation. Ask early.
Ask your lender for an estimate of your cash to close, too. I explain what it includes in Closing Costs in Oklahoma: What Stillwater Home Buyers Should Expect.
A parent buying for a student has the same steps, with a few extra questions for the lender: whose income and credit will be used, who will be on the loan, and whether the student will live in the home or you plan to rent part of it (See Can You Buy a House in Stillwater On a Student Budget). Talk to your lender early. For more on how I help OSU parents, see my OSU parent-buyer page.
What is the difference between pre-approval and pre-qualification? Pre-qualification is a rough estimate based on what you tell a lender. Pre-approval means the lender has checked your documents and credit and issued a letter for a specific loan amount.
Do I need a pre-approval before I look at homes? You can browse before you talk to a lender, but I suggest a conversation early. It tells you your price range, so you don't fall for a home you can't qualify for, and in most cases you'll need a pre-approval letter when you make an offer.
Does pre-approval hurt my credit? A mortgage pre-approval usually involves a credit check, which can lower your score slightly for a short time. Multiple mortgage checks in a short window are typically counted as one. Ask your lender how it works.
How long does a pre-approval last? It varies by lender. Many letters are good for a set period, so ask yours.
Is a pre-approval a guarantee of a loan? No. The loan still has to be underwritten, the home has to appraise, and your finances can't change in a way that affects your approval.
Can I get pre-approved if I'm buying for my child at OSU? Often yes, but your lender will have specific questions about whose income is used and how the home will be occupied. Ask early.
If you're financing, it helps to talk to a lender early, and then we can look at homes. You can see what's available on my homes for sale page, or message me and we'll talk through your plans. Call or text me at 405-614-9600. For the full timeline, see How Long Does It Take to Buy a House in Stillwater?.
Buying a home for your OSU student? Join Stillwater Home Buying for OSU Parents on Facebook, a free group where I share timelines, neighborhoods, and answers to the questions parents ask most: https://www.facebook.com/groups/1388465913401688
Ann Morgan is a REALTOR® with Real Estate Professionals in Stillwater, Oklahoma, specializing in new construction and OSU parent-buyer relocation. A five-time winner of Stillwater News Press's Best Realtor award and a 2026 Best in Stillwater Gold Winner, Real Estate Agent. A consistent top-3 agent in the Stillwater MLS.
This is general information, not financial or legal advice. Talk to a lender about your own situation.
Stay up to date on the latest real estate trends.
Moving to Stillwater
Moving to Stillwater Alone: How to Find Community
Home Buying
What's included, who pays, and how a seller credit can help.
Homes Buying
What each one means, what a lender checks, and which one a seller will take seriously.
Home Buying
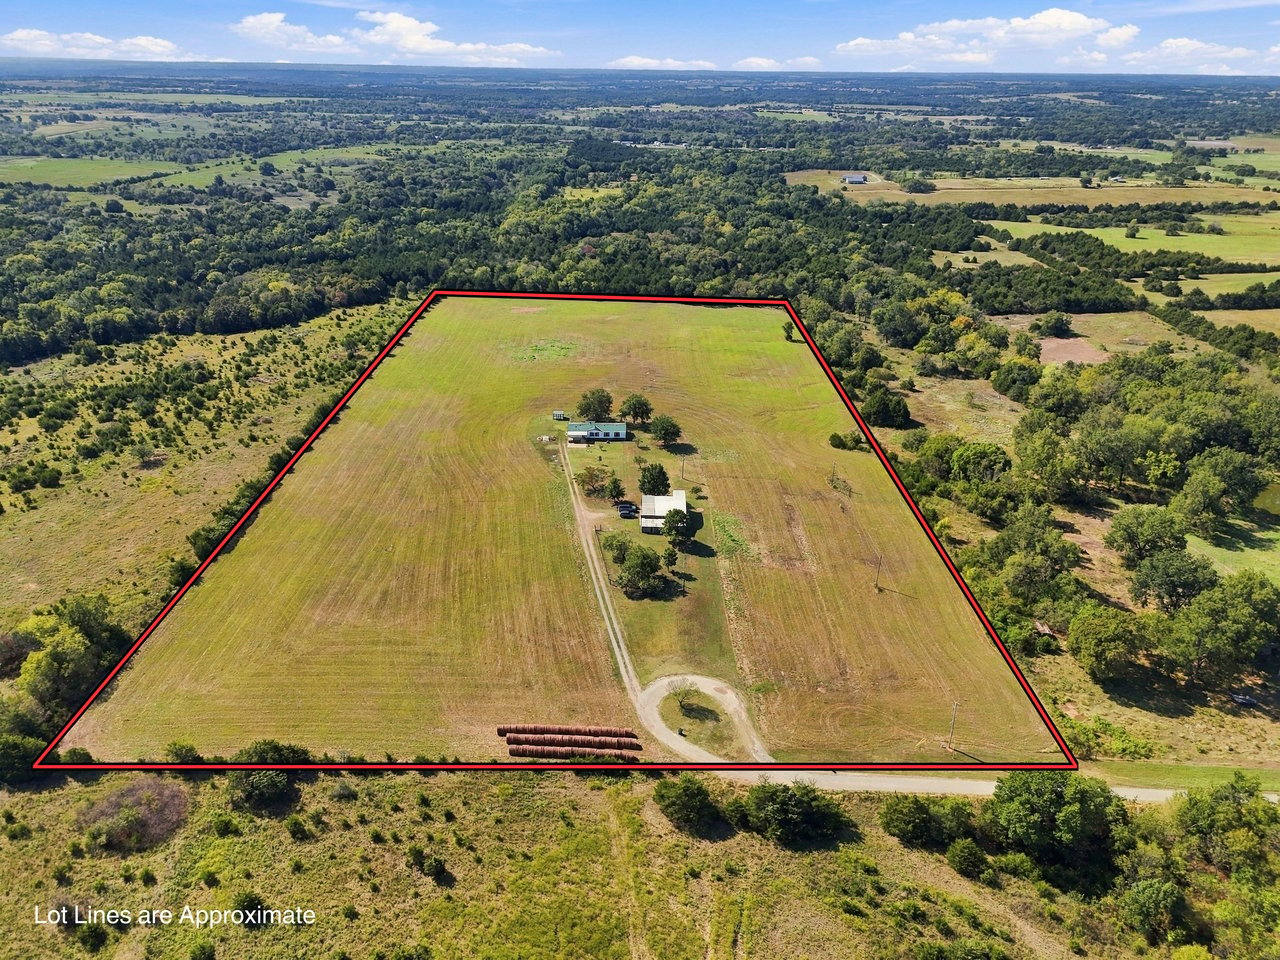
Water, septic, power, access, and mineral rights: the questions that decide whether a piece of land will work for you.
Stillwater Oklahoma
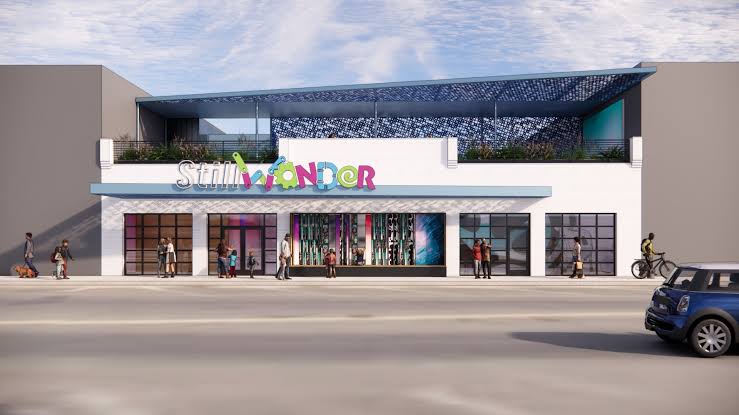
Time, place, parking, and how to plan the morning around the OSU game, plus where the children's museum project stands.
Living in Stillwater
Where to go for birthdays, brunch, date night, game day, and the day you close on your new home.
Market Update
More homes listed, fewer sold, and sellers getting a little less of their asking price.
Stillwater Realtor
Utilities, insurance, property taxes, and the one-time costs of moving in, with real numbers and where they come from.
Buying a Home
What four real Stillwater homes, from $240K to $585K, cost per month and in cash at today's rates, and how to bring it down.
Get help determining your property's current value, crafting a competitive offer, writing and negotiating a contract, and more. Contact me today.