What Are Seller Incentives? How a Seller Credit Can Lower Your Payment or Cash to Close in Stillwater
Buying a Home Ann Morgan
Buying a Home Ann Morgan
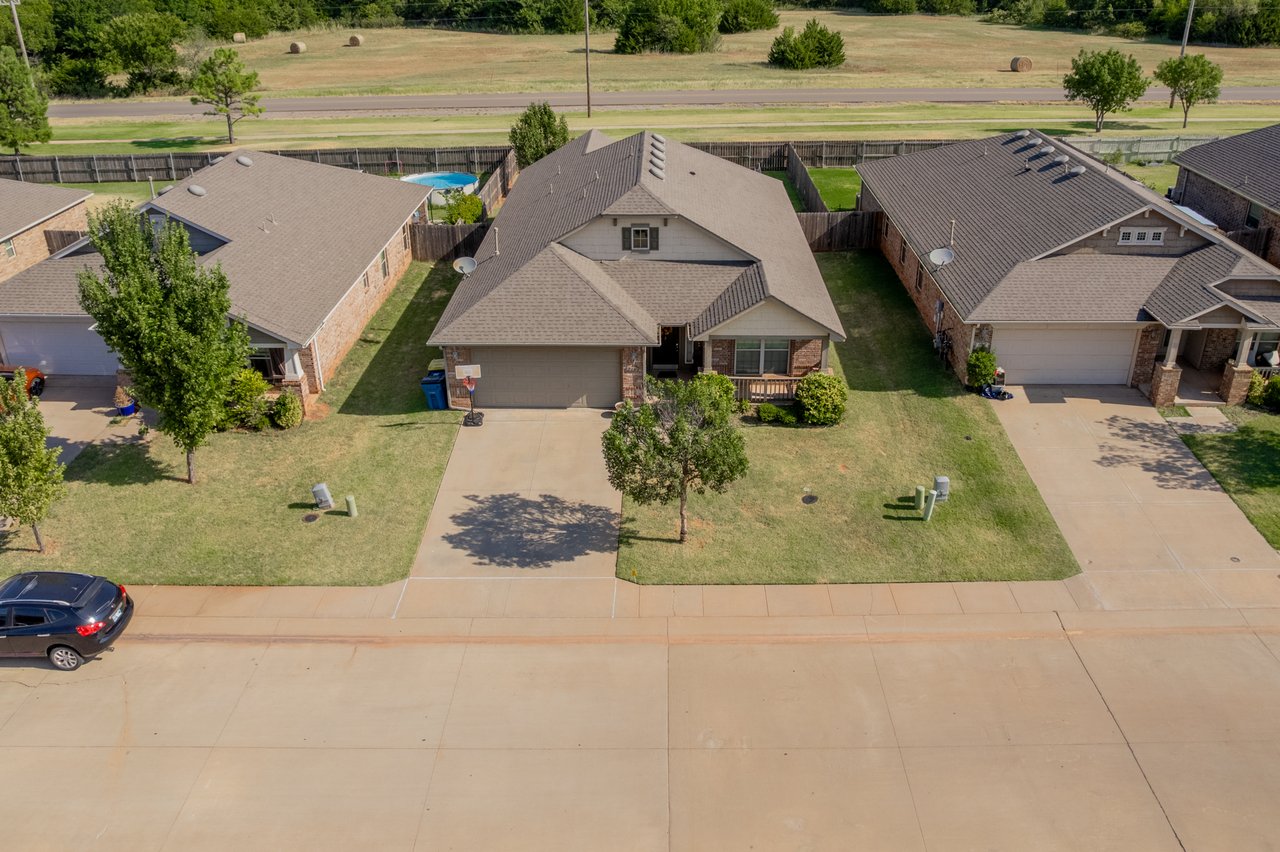
A seller incentive is money the seller agrees to put toward your purchase instead of dropping the price, and a buyer can use it to lower cash at closing, buy down the interest rate, or both. In Stillwater right now, two of my listings are offering exactly that: the sellers of 218 E Copper Canyon are offering up to $7,800, and the sellers of 1122 E Swim are offering up to $7,200. Here's how seller incentives work, the four ways to use one, and what each choice does to your numbers.
A seller incentive, also called a seller concession or seller credit, is an agreement in the contract that the seller pays part of your costs at closing. It doesn't change the price on the page. It changes what the purchase costs you. Common uses:
Seller help generally can't be used for your down payment, and it can't be more than your actual eligible costs. Each loan type also limits how much seller help is allowed. Your lender confirms the limits for your loan. See How Do Rate Buydowns Work?.
Because buyers have more choices than they did a few years ago, and rates are still high. Nationally, sellers outnumbered buyers by 57.9% in August and sellers gave a concession in 44.7% of sales, according to Redfin data cited by Keeping Current Matters. Those are national numbers, and Stillwater is its own market, but the pattern shows up locally too. A credit lets a seller help a buyer with the payment without lowering the listed price, which matters for the home's value and for the neighbors' comparable sales. See Is Stillwater a Buyer's Market Right Now?.
Both of these homes use the same assumptions: 20% down, a 30-year fixed loan, and an example rate of 7.32% (the Freddie Mac weekly average for Oct 22, 2026). Closing costs are estimated at 3% of the loan. Monthly figures are principal, interest, and HOA only, so property taxes and insurance would be added on top. These are estimates, not a loan quote.
218 E Copper Canyon | 1122 E Swim | |
|---|---|---|
Neighborhood | The Canyons, north Stillwater | Eastridge, northeast Stillwater |
List price | $342,800 | $315,000 |
Details | 1,959 sq ft, built 2016 | 1,776 sq ft, built 2020 |
HOA | $360 a year | $175 a year |
Seller help | Up to $7,800 | Up to $7,200 |
Down payment (20%) | $68,560 | $63,000 |
Estimated closing costs | about $8,227 | about $7,560 |
Estimated monthly with no help | about $1,914 | about $1,746 |
Here's what each way of using the seller's money does.
If the buyer chooses... | 218 E Copper Canyon | 1122 E Swim |
|---|---|---|
Less cash at closing | $7,800 less to bring to closing | $7,200 less to bring to closing |
Lower payment for good (permanent buydown, rate to about 6.61%) | about $131 less per month, for all 30 years | about $121 less per month, for all 30 years |
Lower payment for 2 years (2-1 buydown) | about $358 less per month in year 1 and $183 less in year 2, with about $1,316 left for closing costs | about $329 less per month in year 1 and $168 less in year 2, with about $1,242 left for closing costs |
Lower price instead (no seller help) | price of $335,000, about $43 less per month and about $1,747 less at closing | price of $307,800, about $40 less per month and about $1,613 less at closing |
The buydown estimates assume about 0.25% off the rate for each 1% of the loan paid in points. Your lender sets the real pricing, so use these to compare options, not as quotes.
Choose less cash at closing if cash is your biggest limit. You keep more in the bank for the move, furniture, or a repair cushion.
Choose a permanent buydown if you plan to stay for years and want the lower payment locked in. On these homes the seller's money pays for itself in about 60 months of savings, so it makes the most sense if you keep the loan five years or longer.
Choose a 2-1 buydown if you want the biggest drop in the first two years, for example while you settle in or expect your income to rise. It also fits buyers who may refinance if rates fall. It isn't a guarantee that you can refinance, because that's a new loan you'd have to qualify for. After year two the payment returns to the full-rate amount, so be sure you can afford that number.
Choose a lower price if you'd rather have a smaller loan on paper. The seller's money goes the least far this way: on both homes, the same dollars as a permanent buydown lower your monthly payment about three times as much as a price reduction would. The price can still matter for taxes, resale, and appraisal.
Each listing has its own offer-plan page. Pick how you'd use the seller's help and it shows your estimated cash to close and monthly payment, then builds a plan you can send to your agent (or to me if you don't have one yet):
For other homes, my Buyer's Purchasing Power calculator shows how a rate or buydown changes a payment.
What is a seller credit? It's money the seller agrees to pay toward your closing costs, prepaids, or rate buydown. The price stays the same.
Can I use a seller credit for my down payment? Generally no. Seller help covers closing costs, prepaids, and buydown costs. For down payment help, see Down Payment Help for Oklahoma Home Buyers.
Is a seller credit better than a lower price? Often it helps your payment more, especially as a rate buydown, but it depends on your loan, your plans, and the appraisal. Run both with your lender.
Is a 2-1 buydown or a permanent buydown better? A 2-1 gives a bigger payment drop for two years. A permanent buydown gives a smaller drop for the whole loan. Choose based on how long you'll keep the loan.
Do the sellers of both homes offer the same thing? Each listing has its own terms. 218 E Copper Canyon is offering up to $7,800, and 1122 E Swim is offering up to $7,200.
Tell me which home you're looking at and I'll walk through the numbers with you, then help you write an offer that uses the seller's help the way that fits your plans. Reach out and we'll start with a conversation.
Thinking about moving to Stillwater? Join the Moving to Stillwater group on Facebook to ask questions and get local answers: https://www.facebook.com/groups/534271350873991
Ann Morgan is a REALTOR® with Real Estate Professionals in Stillwater, Oklahoma, specializing in new construction and OSU parent-buyer relocation. A five-time winner of Stillwater's Best Realtor award and a consistent top-3 agent in the Stillwater MLS.
I'm a REALTOR®, not a lender. Figures are estimates for comparison, not a loan quote. Seller help limits, rates, and buydown costs depend on your lender and loan type.
Sources: Listing terms for 218 E Copper Canyon and 1122 E Swim (current as of Nov. 2, 2026); Freddie Mac weekly 30-year average (Oct. 22, 2026) for the example rate; Redfin data via Keeping Current Matters (national seller concession and buyer-seller figures).
Stay up to date on the latest real estate trends.
Buying a Home
Four ways to use seller help, with real numbers from two Stillwater homes.
Buying a Home
Low-down-payment loans, OHFA assistance, gift funds, and builder help, explained for Stillwater buyers.

Buying a Home
What lenders look for, what's changing in 2026, and how on-time rent may start to count.
Buying a Home
A simple way to compare the two, what the full cost of owning includes, and when each one makes sense.
Buying a Home
How taxes are calculated, the homestead exemption, when they're due, and how to estimate them for any home.
Moving to Stillwater
How to prepare, what to ask, and how to check the flood zone for any address.
Stillwater Oklahoma
Season two runs Nov. 7 through Jan. 23, with hours, prices, and a downtown date-night plan.
Buying a Home
Why being ready matters more than the calendar, and what the seasons can mean for buyers here.
New Construction
What the homes offer, what Lennar is offering now, and what to ask before you buy.
Get help determining your property's current value, crafting a competitive offer, writing and negotiating a contract, and more. Contact me today.